What is the market overview for the Iron And Steel Mills And Ferroalloy Market?
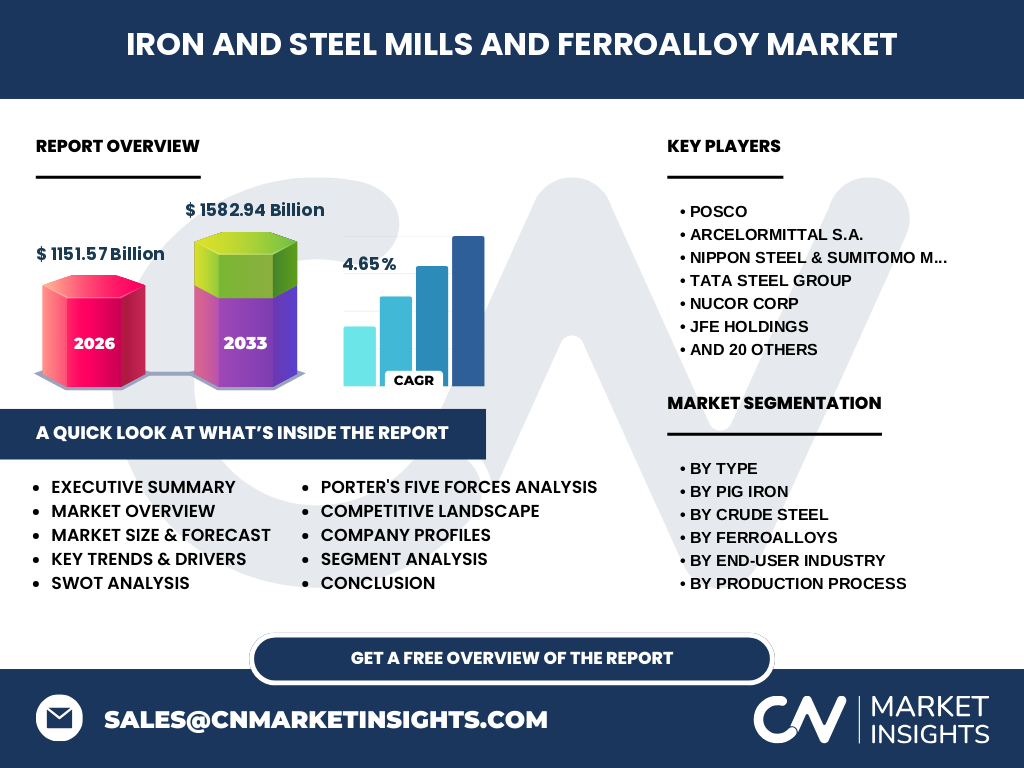
Our analysis indicates that the Iron And Steel Mills And Ferroalloy Market encompasses primary metal manufacturing, covering crucial intermediate materials like pig iron and specialized ferroalloys. Valued at 1151.57 Billion in 2026, this sector forms the foundational backbone of global industrialization, supplying critical inputs for heavy machinery, automotive assembly, and expansive infrastructure projects worldwide.
Structural Growth Drivers and Market Restraints
Based on our research, the Iron And Steel Mills And Ferroalloy Market is propelled by surging infrastructure spending across emerging economies and rising demand for lightweight automotive alloys. However, persistent market restraints include strict environmental regulations curbing carbon-heavy blast furnaces and volatile raw material pricing for metallurgical coal and iron ore, creating significant margin pressures for producers.
The Shift Toward Decarbonization and Advanced Alloys
Industry trends reveal a pronounced migration toward Electric Arc Furnace (EAF) production routes to lower carbon intensity. Key steelmakers are actively investing in green hydrogen reduction technologies. This strategic pivot favors agile operators capable of supplying high-purity stainless steel and specialized ferrochrome to meet stringent modern regulatory standards.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted global supply chains, halting operations across major ports and plunging industrial demand. Nevertheless, the Iron And Steel Mills And Ferroalloy Market exhibited a robust recovery trajectory. Post-lockdown stimulus packages targeting green infrastructure accelerated output, pushing market valuations toward the 1582.94 Billion forecast mark by 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration is notably high, dominated by industrial giants like China Baowu Steel Group, ArcelorMittal S.A., and Nippon Steel. Strategic dynamics focus on vertical integration, securing captive iron ore mines, and acquiring boutique ferroalloy producers to insulate profit margins against raw material shocks and trade tariff fluctuations.
Executive Summary of the Iron And Steel Mills And Ferroalloy Market
Our comprehensive evaluation confirms that the Iron And Steel Mills And Ferroalloy Market stands at 1151.57 Billion in 2026 and is projected to expand to 1582.94 Billion by 2033 at a steady 4.65% CAGR. Stakeholders must navigate stringent carbon caps while capitalizing on surging demand from renewable energy infrastructure and advanced manufacturing.
Market Forecast from 2027 to 2033
The data suggests sustained expansion for the Iron And Steel Mills And Ferroalloy Market, scaling from 1151.57 Billion in 2026 to reach 1582.94 Billion by 2033. Achieving this trajectory requires a compound annual growth rate of 4.65%, heavily underpinned by technological upgrades in energy-efficient smelting and expanding applications in electric vehicle manufacturing.
Segmentation Analysis of Production Routes and End-Uses
The Iron And Steel Mills And Ferroalloy Market segments comprehensively by product type, including Ferroalloys, Pig Iron, and Crude Steel (further broken into carbon, alloy, and stainless steel). Production processes range from the traditional Blast Furnace–Basic Oxygen Furnace (BF–BOF) route to modern Electric Arc Furnace (EAF) and Submerged Arc Furnace (SAF) methods serving automotive, construction, and oil sectors.
Regional Market Analysis and Geographic Distribution
Geographic performance highlights Asia-Pacific as the dominant revenue generator, driven by massive urbanization projects and industrial capacity in China and India. Meanwhile, North America and Europe prioritize high-value alloy steel and low-carbon production processes, complying with strict regional emissions mandates enforced by local environmental protection agencies.
In-Depth Regional Review
A granular review of regional performance reveals that Asia-Pacific commands over half of the global share, supported by dominant producers like POSCO and Tata Steel Group. Conversely, European markets face severe regulatory headwinds under the Carbon Border Adjustment Mechanism, compelling firms like Thyssenkrupp AG to accelerate green hydrogen steel initiatives.
Company Profiles and Strategic Positioning
Leading industry participants leverage distinct competitive moats. Nucor Corp dominates scrap-based EAF recycling in North America, while ArcelorMittal S.A. maintains a massive global footprint focusing on advanced automotive grades. Asian powerhouses like Nippon Steel and Baoshan Iron & Steel prioritize high-tensile architectural steels and proprietary electrical steel coatings.
Porter's Five Forces Analysis
Our analysis indicates that supplier power remains moderate-to-high due to consolidated iron ore mining cartels. Threat of substitutes is remarkably low given steel's unmatched structural integrity. However, competitive rivalry is fierce among established titans like JFE Holdings, Gerdau S.A., and Severstal, driving continuous cost-optimization initiatives.
SWOT Analysis of the Industry
Strengths include immense capital asset infrastructure and deeply integrated supply chains. Weaknesses involve high greenhouse gas emissions and heavy reliance on coking coal. Opportunities abound in green steel branding and high-purity ferrovanadium applications. Threats stem from geopolitical trade disputes, carbon taxation, and fluctuating raw material logistics.
Value Chain Analysis
The value chain flows from raw extraction of iron ore, metallurgical coal, and quartzites through reduction smelting into pig iron and ferroalloys. Subsequent refining produces crude steel variants before fabrication for end-users in automotive, energy, and construction. Mid-stream efficiency dictates overall profitability across the entire ecosystem.
Investment Insights and High-Potential Areas
Strategic recommendations highlight Submerged Arc Furnace (SAF) tech upgrades and green hydrogen reduction projects as primary high-potential investment zones. Investors should target mills integrating renewable energy microgrids to insulate against rising electricity tariffs and strict carbon compliance penalties expected through 2033.
Conclusion and Key Takeaways
In summary, the Iron And Steel Mills And Ferroalloy Market represents a resilient, evolving sector bridging traditional heavy industry with modern sustainability goals. Propelled to 1582.94 Billion by 2033, long-term success heavily depends on swift decarbonization strategies and technological adoption across both EAF and BF-BOF manufacturing routes.
Research Methodology
Our baseline estimates are rigorously triangulated by combining official trade registry data from international metal associations, primary stakeholder interviews with C-suite executives at firms like Cleveland-Cliffs and Ternium S.A., and secondary macroeconomic indicators tracking global construction output and automotive manufacturing indices.
Scope of the Report
This report covers global market parameters for the Iron And Steel Mills And Ferroalloy Market from 2026 to 2033. Limitations include unforeseen geopolitical trade embargoes, sudden shifts in maritime shipping freight rates, and volatile national energy subsidies affecting regional smelting operational costs.
Recent Developments and Strategic Moves
Recent industry momentum features major announcements, including joint ventures by Evraz, Novolipetsk Steel (NLMK), and Metalloinvest focused on low-emission pellet production. Furthermore, Hyundai Steel Company and Kobe Steel Limited have forged green technology partnerships to commercialize hydrogen-based direct reduction iron processes.